Tuesday, August 23, 2016

Head Scratcher

I do not understand why New York REIT, Inc. (NYRT) is planning to liquidate.  NYRT is a former non-traded REIT that listed on the New York Stock Exchange in April 2014.  It is associated through management with AR Global.  NYRT has been battling outside institutional investors that opposed NYRT's planned merger with JBG Companies and certain of JBG Companies' private funds.  The merger was cancelled in early August. 

So the JBG Company merger did not happen and NYRT decides its only option is to sell all its properties?  NYRT's second quarter 10-Q states the REIT has $2 billion in assets and nineteen properties.  This Bloomberg article reports on institutional investor skepticism about the planned liquidation, including from WW Investors, the firm that helped end NYRT's merger with JBG Companies.   The asset sale and liquidation plan, like the JBG Companies merger, faces outside resistance as noted by this quote from the Bloomberg article:

Sheila McGrath, an analyst at Evercore ISI, said the New York-based company had better options than the liquidation and that a new board of directors must be installed immediately.
“This is the same board that approved the JBG merger transaction at a significant cost to shareholders,” McGrath wrote in a research note Monday. “The one thing that most institutional investors that we have spoken to support is the recasting of the NYRT board as soon as possible prior to making any final strategic decision.”
 There is plenty of drama yet to come for NYRT.

Monday, August 15, 2016

Crazy Stuff

This is wild story on Bloomberg.  The SEC today suspended a $35 billion company based in Northern Baja California.  Neuromama's stock was halted until August 26 “because of concerns regarding the accuracy and adequacy of information in the marketplace about, among other things, the identity of the persons in control of the company’s operations and management, false statements to company shareholders and/or potential investors that the company has an application pending for listing on the NASDAQ Stock Market, and potentially manipulative transactions in the company’s stock.”

Neuromama's stock has quadrupled so far in 2016 despite not having filed filed financial statements since 2013, and then it had no revenue.  This section gives no comfort:
Steven Zubkis, who also goes by Steven Schwartzbard, is the marketer behind Neuromama, according to the company’s website. He left prison in August 2010 after being sentenced for five years for defrauding investors, in a $1.8 million scheme through misrepresentations tied to the renovation of a Las Vegas casino. The Ukrainian immigrant was sued by the SEC in the 1990s for orchestrating a $12 million penny stock scam. He was ordered to pay more than $21.6 million in disgorgement and penalties for selling unregistered securities from 1993 to 1996.
In what business does a company named Neuromama operate?  The Bloomberg article states that it "operates in a broad range of businesses: a search engine, licensing “heavy ion fusion technology patents,” and Cirque-du-Soleil-style performances in Tijuana, to name just a few."  Well, that explains things.

Blackstone's Non-Traded REIT

Here is a Bloomberg article on Blackstone's new $5 billion non-traded REIT - $4 billion initial offering with $1 billion of distribution reinvestment - which was filed last week with the SEC.  The article states that the new REIT will address transparency issues that have plagued other non-traded REITs.  The article does not state how the Blackstone non-traded REIT is more transparent than other non-traded REITs.  Unsubstantiated comments like this annoy me.  Most non-traded REITs have decent transparency, you just have to take the time to read filings.  I am not sure what Blackstone plans to disclose that other REITs do not.

The Bloomberg article has a positive quote from a Green Street Advisors managing director:
“Historically, the fee load has been pretty significant for retail investors to get into these vehicles,” said Dirk Aulabaugh, a managing director in the advisory and consulting unit of Green Street Advisors LLC, a Newport Beach, California-based real estate research firm. Blackstone’s new fund appears to be “better aligned than what has historically been the case in the nontraded REIT space, and I think investors are going to welcome that, and they’ll be successful in raising capital along those lines.”
Like the transparency issue, the article implies through the quote above that the Blackstone non-traded REIT has a better fee structure than other non-traded REITs, but it offers no specific comparisons.  I guess I am going to have to read through the dang filing to find out for myself.

Friday, August 12, 2016

D'oh!

A DI Wire headline today states that "MVP REIT Reports 94 Percent Increase In Year-Over-Year Revenues."  Amazing! Stupendous! Fantastic! Misleading!  The REIT was raising and investing money over this period, so a 94% revenue increase needs more context.  A REIT raising equity and borrowing money to buy properties better be increasing revenue. Year-over-year financial performance for any investment in the midst of raising and investing capital is non-comparable.

Let's take a look at some of MVP REIT's other year-over-year financial points of interest from the same financial statement along with sample headlines:
  • Assets increased 59% from $81 million to $129 million.  "MVP REIT's Total Asset Skyrocket 59%"
  • Debt increased 75% from $25 million to $44 million.  "Burdened:  MVP REIT's Debt Leaps 75%"
  • MVP's Net Loss for the six months ended June 30, 2016 was ($2,131,000) compared to a Net loss of ($1,572,000) for the six months ended June 30, 2015, a drop of 39%.  "Oops, MVP REIT's Net Loss Moves In Wrong Direction, Dropping 39%"
  • MVP's Cash From Operations for the six months ended June 30, 2016 was ($1,159,000) compared to Cash From Operations of ($1,347,000) for the six months ended June 30, 2015, an improvement of 14%.  "MVP REIT Slows Hemorrhage of Operating Cash"
All the headlines are right, and all are misleading.  Only when MVP REIT has several quarters of fully invested operations will period-over-period comparisons be relevant.  One point that is true about MVP REIT, and that is not obfuscation, is that it is a small REIT.  It only raised $97 million in equity in its offering and has $129 million in total assets.

Thursday, August 11, 2016

Looking Through The Rearview Mirror

I read last week that FINRA has launched an investigation into non-traded business development companies (BDCs).  FINRA is late to this issue, like about three years too late.  Non-traded BDC sales are down a staggering 63% through the first seven months of 2016 compared to the same period in 2015.  The drop can be attributed, in part, to the closing of Franklin Square's FSIC III and CNL's Corporate Capital Trust, two of the top selling non-traded BDCs, and the tepid reception of their respective follow-on offerings.  The decline in sales is also related to the lower NAVs reported by many BDCs over the past year and a half, which served to spook clients and financial advisors.  Non-traded BDCs are required to value their portfolios quarterly, or more frequently if their NAVs move outside pricing bands, and non-traded BDCs have shown they are not immune to market forces.

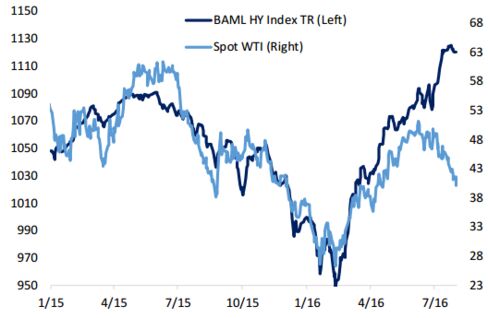
The drop in oil prices that started in the second half of 2014 was felt across high yield markets, and therefore by non-traded BDCs.  The oil and gas sector is heavily represented in the high yield debt sector, and the graph I presented my previous post illustrates how correlated oil prices and the high yield markets were until earlier this year.

BDCs are a structure, not an asset class.  Most non-BDCs operate in the large non-bank financing market, primarily making a variety of loans to small and medium sized companies.  Companies that borrow from BDCs and other non-bank lenders are generally growing companies that do not have banking relationships or cannot get bank financing, and therefore do not have investment grade credit ratings, if they have a rating at all.  This is a high yield market and comes with all the risk of high yield investing.

I have seen various numbers related to the size of the non-bank capital market, but the smallest figure I have seen is $1 trillion and the largest over $50 trillion.  This is a legitimate market that is not going away anytime soon.  Non-traded BDCs are a small part of this huge market.

Wednesday, August 03, 2016

Oil and High Yield Debt

Here is a good Bloomberg article on the rebound in high yield debt and the oil markets.  For much of the past year and a half the price of oil and high yield debt have moved together.  The latest drop in oil prices has been a solo move, as high yield debt has not followed the oil market down.  The following chart from the article shows the performance of oil and high yield debt since the start of 2015:


High yield debt market moved with oil because so many recent issuers of high yield debt were oil and gas companies.   A May 31, 2016, report by the law firm Haynes & Booth states that there have been 81 oil and gas bankruptcies since the start of 2015.

The Bloomberg article takes a closer examination of the high yield debt and oil markets.  When just the high yield debt of energy companies is compared to the price of oil, the performance is strikingly similar.  While the overall high yield market may have separated from oil, energy high yield debt is following the price of oil down.

Update:  As of August 3, 2016, the number of oil and gas bankruptcies since the start of 2015 is now up to 85.

Friday, July 29, 2016

Posting Again

It is time to start reposting.  I never formally stopped writing this blog so I am not formally restarting it.  There is a mealy-mouthed cop-out if ever there was one.

The primary reason I decided to restart posting is the DI Wire.  I have been getting its daily updates on the Direct Investment (DI) industry for a year or more and still have not figured out its mission.  Is it news?  Paid advertisement?  A mixture of both?  The best I can figure the DI Wire is mostly the PR Wire.  The tipping point for me was earlier week when a headline announced that Benefit Street was to acquire Business Development Corporation of America (BDCA).  Wrong.  As subsidiary of Benefit Street is acquiring BDCA's advisor from AR Global, and it is not acquiring BDCA.  The headline, which has not been corrected, implied a liquidity event for BDCA investors.  Wrong.  BDCA investors will have a new investment manager, not liquidity.  Big, big difference.

Of course I will continue to read the DI Wire, I love to read stories about direct investment sponsors hiring wholesalers or random acquisitions in line with investment objectives.

The Clock Is Ticking...

On July 25, 2016, UDF IV received written notice from Nasdaq Hearings Panel that Nasdaq Global Select Market will continue to list UDF IV stock.  UDF IV's stock is currently halted.  The Nasdaq decision is contingent upon UDF IV meeting certain listing requirements, in particular it has to file with the SEC 2016's first and second quarter financial statements and 2015's audited financial statements by September 12, 2016.

UDF IV's auditor resigned last November.  A new auditor, EisnerAmper, LLP, was announced on June 8, 2016, which was good news for the mortgage REIT.  The new auditor is presumably working to complete UDF IV's financial statements before the September deadline.  I expect ugly results when and if UDF IV's stock is allowed to resume trading as investors will rush to exit.  Audited financial statements or not, UDF IV remains under investigation by the FBI and SEC and is in default on a term loan that had $28.5 million outstanding as of May 23, 2016.  The following passage from UDF IV's 8-K filing describing the default shows the level of financial restrictions it faces as a result of the default:
The Trust (UDF IV) is required to use a portion of its future available cash flow to pay transaction expenses, interest due under the Loan, and principal. The Trust has agreed to provide certain financial reporting to the Lenders and it has agreed to suspend distributions to its shareholders during the Forbearance Period. The Trust also agreed not to originate new mortgage loans, incur additional debt, grant additional or substitute collateral to any other lender, or dispose of assets without first obtaining the consent of the Lenders.
 I want UDF IV to resolve its issues.  Its financial statements are at the top of my summer reading list.

Wednesday, April 29, 2015

Good Advice

Here is a Bloomberg article that quotes Colony Capital's Thomas Barrack, Jr.   Mr. Barrack provides some smart, basic advice, but advice that few people will follow.  This passage is a warning:
“Everybody is outside of their own asset class,” Barrack said in a Bloomberg Television interview Tuesday with Erik Schatzker and Stephanie Ruhle at the Milken Institute Global Conference in Beverly Hills, California. “When amateurs enter the marketplace for all of this, you are going to get an abundance of something and it is usually not good.”

Central banks globally have pushed investors into higher-yielding assets by reducing interest rates and purchasing bonds. The Standard & Poor’s 500 Index reached an all-time high on Friday and sovereign debt in Europe is trading at negative yields.

“Institutional investors that are in this endless search for yield are ignoring the risk peril of all the consequences of those things,” he said.
And here is some more:
To protect themselves from possible future losses, real estate investors should look for “equity-type returns” in the capital stack, Barrack said during the panel discussion.

“Floating debt can choke and kill you quickly,” he said.
The article is about real estate investors, but you can substitute nearly any asset class that throws of yield and uses low cost leverage to boost returns. 

InvenTrust

Inland American changed its name to InvenTrust Properties Corp on April 16, 2015.  I would have posted earlier but I am still laughing at this nonsense name.  Inland needs to invent some equity for Inland American investors rather than waste time and money thinking of a made-up name.   The new logo is cool, although I am not sure what it signifies.


InvenTrust's spin-off of Xenia Hotels and Resorts (XHR) has held up well in the market since its listing in February.  It has traded over $22 per share since mid-March.  Inland has had more good news, as its latest non-traded REIT, Inland Real Estate Income Trust, raised over $88 million in March, placing it third out of all non-traded REITs in sales.  Not too shabby.

Friday, March 27, 2015

Tedious

The lazy reporting on non-traded REITs is getting tedious.  Few journalists that write articles about non-traded REITs fully understand them, and it shows.  The latest installment is from the March 24, 2015, Wall Street Journal, in an article titled "Property Investors' Latest Horror: Zombie REITs."  The article focuses on two pre-crash REITs, and not all the liquidity events over the past two years.  The article's focus was Inland American and CNL Lifestyle, two REITs I have recently posted about.  There is no way to spin the poor performance of these two REITs, but they are not the entire market, and their struggles are not new news. 

The article states that the value of Inland American's holdings has plunged 60%.  Wrong.  This is based on the $10.00 per share price that investors paid for their shares and the recently announced $4.00 per share value.  The difference between the original $10.00 per share and current estimate of $4.00 per share is indeed 60%, but it excludes the value of the Xenia Hotels & Resorts (XHR) spin-off that all Inland American investors received.  I figure the listing of XHR was worth approximately $2.80 per share to Inland American investors, or 28% or their original investment (and XHR stock has gone up since its listing).  The article mentions XHR, but not the amount returned to investors.  The amount investors received in XHR needs to be added to Inland American's remaining value.  Inland American still has its issues and investors are still at a loss, but the XHR listing was a major event.

The article further states (my emphasis):
Fundraising by nontraded REITs has now cooled. The funds pulled in about $15 billion in 2014, down by a quarter from 2013, in part because the funds returned just $12.9 billion of investors’ original capital last year, down from $17.2 billion in the previous year.
My own research showed $13.5 billion of original equity experienced liquidity events in 2014, not $12.9 billion.  If you use the WSJ numbers, in two years there was over $30 billion of liquidity.  If you look back at the lack of liquidity in the '80s, '90s, and '00s, $30 billion of capital returned to investors in a two-year span is stunning.

(There is more than a small irony that the article complains about 2014's drop in fund raising for non-traded REITs due to the decline in liquidity events.  Selling a REIT upon its liquidity event to reinvest in another non-traded REIT is a story in itself and a bigger industry-wide issue than two well-known, struggling REITs.)

Journalists and business publications have to get better covering and understanding non-traded REITs (and their sort of brethren business development companies).  These investments have raised billions since 2008, and to sound alarms and recyle old themes without addressing current issues is not helping investors.  The only thing missing from this article was as a Leo Wells reference.

Tuesday, March 24, 2015

Return for Risk?

As a follow-up to my post yesterday about interval funds, I encourage you to click through to view the portfolio for Ladenburg Thalmann's Alternative Strategies Fund (LTAFX).  When you finish picking up your jaw, click here to see LTAFX's returns and determine for yourself whether investors have been properly compensated (through high returns) given the risk of some of the interval fund's holdings. 

Oil Storage Problem

Bloomberg has an article and animated video on its website that present a scenario where oil could go to $20 a barrel or lower if oil storage reaches capacity.  The article is full of hypothetical situations, but it reinforces my feeling that no one knows where the price of oil is headed.

Monday, March 23, 2015

High Priced Mediocracy

Interval funds - generally, continuously offered closed-end funds - give investors a chance to invest in multiple alternative investments they may not otherwise qualify for directly.  I am specifically discussing interval funds that focus on acquiring interests in business development companies, public REITs, private REITs, private equity real estate funds, private placements, and public, non-traded REITs.  These interval funds are similar to mutual funds, so suitability requirements are much lower than a direct investment into one of the non-traded investments owned by the interval fund. 

My knocks on interval funds are fees and performance.  Interval funds are funds-of-funds.  This means there are two layers of fees - one at the interval fund level and one at the underlying investment fund level.  The combined annual expenses can run three percent to five percent of total assets, which is a big hurdle for asset classes and investments - real estate and business development companies - that are historically income oriented, not growth focused.  Funds-of-funds will have average performance, as top performing funds' results are offset by the results from poor performing funds.  Over the long-term, for most investors, I don't believe the portfolio benefits of an interval fund - diversification and lower volatility - outweigh the performance issue, which is inherent because of interval funds' structures, and diminished further by their high fees.

Thursday, March 19, 2015

Growing Glut

I am fascinated by the drop in oil prices.  No one predicted the price drop of the past six months.  No one knows if oil prices are going to $80 a barrel or $20 a barrel.  (There are guesses at both ends of the spectrum, so some analyst will be able to claim prescience.)  The attached Bloomberg article and the chart below are from last week but give an indication of where prices are likely to go, at least in the near term.


Friday, March 13, 2015

Bad Guess

Last week I guessed at a price of $6.50 per share for CNL Lifestyle's new net asset value.  I was not close, not even in the same county close.  In an 8-K filing on March 10, 2015, CNL Lifestyle disclosed a new NAV estimate of $5.20 per share, down 24% from the $6.85 per share estimate at the end of 2013.  Read the 8-K, the candor of certain statements is jarring, like the following passages that help explain why the REIT's NAV dropped from $6.85 per share to $5.20 in one year:
Based on discussions between Jefferies and more than 150 potential buyers over the course of the last year, the Company has determined that the value of its assets is lower than the NAV per share of common stock as of December 31, 2013 (the “2013 NAV”). This price discovery data was not available in prior valuations and represents the most significant factor in the decrease of the 2014 NAV from the 2013 NAV. 
Another factor driving the reduction of the 2014 NAV was portfolio performance that, in certain instances, did not meet the Company’s, its operators’ or CBRE’s forecasts. 
CNL Lifestyle's investment banker, Jefferies, shopped the REIT and its assets to more than 150 potential buyers and was told that the $6.86 per share price was too high ("price discovery").  In addition, the assumptions (i.e. net operating income, cap rates, etc.) the REIT used to determine value in early 2014 were too optimistic.  This REIT purchased plenty of niche assets during a real estate boom, so you can't play revisionist today, but a near halving of value is still ugly.

Thursday, March 05, 2015

Wrong On Many Levels

I am hearing some crazy things about American Realty Capital Properties (ARCP), Cole, and RCS Capital (RCAP).  The rumors and finger pointing are flying around so fast someone is going to lose an eye.  Then I read a blog post on an advisor rumor website (I am not going to link to it) that is so wrong it would be laughable if it was not scary.  The post is essentially long quotes from several broker dealer analysts upset by changes at Cole Capital.  The problem is that the article flips back-and-forth, confusing ARCP, which owns Cole Capital, and RCAP, which owns broker dealers and distributes AR Capital-sponsored alternative investments, and treats the two companies as one entity.  If we have learned anything over the past four months it is that ARCP (and Cole) and RCAP are separate companies.  If you are going to spread rumors, at least get the companies straight.

Tuesday, March 03, 2015

Head's Up

CNL Lifestyle REIT announced (warned) today that it is disclosing its net asset value per share on March 10, 2014.  I can hardly wait.  Lifestyle's NAV last year was $6.85 per share.  In 2014, Lifestyle sold its golf properties and used most of the proceeds to pay off mortgage debt related to the golf properties and pay down the REIT's line of credit.  Lifestyle has not returned any capital to investors from property sales.  Lifestyle is still planning on completing its liquidation by December 31, 2015, according to its third quarter 2014 10-Q.  At what share price do we set the over/under for the new NAV?   I'll guess $6.50 per share.

Monday, March 02, 2015

The Wait Is Finally Over

American Realty Capital Properties, Inc. (ARCP) filed its restated financial statements this morning, which stem from the October 29, 2014, disclosure of accounting errors .  The restatement includes the first two quarters of 2014, and full years 2013, 2012, and 2011.  According to this Bloomberg article, which quotes a JP Morgan analyst, it does not appear that any bigger issues emerged from the restatements.  The specter of some undisclosed issue at ARCP was the concern of most people who follow the non-traded REIT industry.  The restatement did result in ARCP reporting an increased loss and lower adjusted funds from operations for 2013. 

Friday, February 27, 2015

Not Dead - Unlike Inland American

My blogging hiatus is over.  There was no reason for the lack of posts other than more pressing work.  I won't predict the frequency of future posts, but I expect more posts than there have been recently.

Here is Bruce Kelly's article on Inland American's new Net Asset Value of $4.00 per share.  I need to dive further into this calculation.  My quick takeaway is that despite plenty of asset sales over the past two years, the new, lower NAV per share primarily reflects this year's spin-off of Inland American's remaining hotel assets. 

In 2014, Inland American sold $1.1 billion of hotel properties to NorthStar and $2 billion of properties overall, but didn't return any capital to investors.  In 2013, Inland American closed a portion of a $2.2 billion property sale to various American Realty Capital entities, the balance of which closed in 2014.  I figure Inland American sold over $3 billion of properties from the middle of 2013 through the end of 2014. 

In February 2015, in a separate transaction from the sales in 2013 and 2014, Inland American completed the spin-off and listing of Xenia Hotels and Resorts (XHR), which Inland American formed in 2014. (Inland American retained 5% of XHR.)  Inland American investors received shares in the new hotel company, and I estimate that the XHR transaction was worth the equivalent of approximately $2.60 per share to an original $10.00 per share Inland American investment.

Inland American's new Net Asset Value (NAV) per share is $4.00, as of February 5, 2014.  Its previous NAV (December 31, 2013) was $6.94 per share.   The drop in NAV reflects - mainly - the XHR spin-off.   The XHR transaction was Inland American's first return of capital event - through the distribution of fully liquid XHR shares to Inland American investors -  with Inland American retaining and retiring debt with the net proceeds from the $3 billion in property sales in 2013 and 2014.  An investor that originally purchased Inland American shares at $10.00 per share have $7.40 per share remaining, based on the estimated listing value $2.60 per share for XHR.  The new $4.00 per share NAV needs to be viewed in relation to the $7.40 per share of remaining offer contribution.

Inland American announced a lower distribution with its new NAV.   The new distribution is $.13 per share, a drop from the previous $.50 per share.  The lower yield partially reflects the XHR spin-off, but it is also a cut in yield.  The yield on the new $4.00 per share NAV is 3.25%, but based on original investment amount, this represents a yield of 1.76% on the $7.40 of remaining original contribution value ($.13 / $7.40).  This should be compared to the previous 5.0% yield ($.50 / $10.00 per share).

I'm no revisionist and won't feign shock that the current $4.00 per share NAV - which is net of the XHR transaction - is less than the original $7.40 per share, or the remaining original offer price.  Inland American acquired the bulk of its properites before real estate prices dropped in the late 2000s.  A drop in value below the original offer price is expected.  Its disingenuous to think that Inland American could have somehow missed the decline in real estate values.  That being said, the cut in annual distribution yield from 5.0% to 1.75% is sharp.

I encourage you to read Inland American's September 22, 2014, 8-K.  It details new incentive compensation for Inland American executives, among other items.  I guess the executives realized that the original compensation, which was subordinate to investors getting a full return of capital plus a preferred return, was unobtainable.  Here is some of the language from the filing:
On September 17, 2014, the board of directors of the Company adopted the following three incentive compensation plans (the “Share Unit Plans”): (1) the Inland American Real Estate Trust, Inc. 2014 Share Unit Plan (the “Retail Plan”), with respect to the Company’s retail business; (2) the Xenia Hotels & Resorts, Inc. 2014 Share Unit Plan (the “Lodging Plan”), with respect to the Company’s lodging business; and (3) the Inland American Communities Group, Inc. 2014 Share Unit Plan (the “Student Housing Plan”), with respect to the Company’s student housing business. Each Share Unit Plan provides for the grant of notional “share unit” awards to eligible participants.
Share Units. Subject to applicable vesting conditions, each share unit represents the right to receive a cash payment, or, to the extent provided in the applicable award agreement, shares of common stock of the Company, Xenia Hotels & Resorts, Inc. (“Xenia”) or Inland American Communities Group, Inc. (“IA Communities”), as applicable, in an amount equal to the fair market value of the share unit on a specified date. Share unit awards will vest and become payable on terms and conditions determined by the plan administrator and set forth in the applicable award agreement, including by reference to certain change in control transactions or specified events resulting in a listing of the applicable entity’s shares on a national securities exchange (including an initial public offering) (“Listing Events”). A “change in control” under the Lodging Plan and the Student Housing Plan includes a change in control of the Company, in addition to a change in control of Xenia or IA Communities, as applicable. A “change in control” under the Retail Plan includes only a change in control of the Company.
For purposes of each Share Unit Plan, the “fair market value” of a share unit will be determined by the board of directors in good faith, and prior to a Listing Event, will be determined by reference to the valuation performed as of December 31, 2013, or such other subsequent similar third party valuation performed to estimate the value of a share unit on a fully diluted basis, using methodologies and assumptions substantially similar to those used in prior valuations.
At the time of the September 2014 filing, the Xenia assets, retail properties, and student housing were the main property types left in Inland American's property portfolio.  It is my opinion that Inland American investors will never get a full return of capital.   Inland American executives, therefore, won't get their originally planned revenue sharing (15% of profits after a return of investor capital plus a 10% annual return), and is the reason for the new incentive compensation plans.   The drop in the REIT's share value and performance of the REIT made the original incentive hurdles unachievable.   I am sure Inland American's executives know this better than anyone and have have created a salve to ease their financial hardship - by which I mean a plan to pay themselves despite investors losing capital.  It is a salve that excludes Inland American investors.

Thursday, October 30, 2014

Not Helping

There is plenty of information to analyze with American Realty Capital Properties' (ARCP) disclosure yesterday of accounting errors.  This afternoon, InvestmentNews published a reckless, red herring of an article that did not advance the analysis.  The article's headline states "National Planning Holdings puts kibosh on ARC nontraded REIT sales."  National Planning Holdings represents four broker dealers, but it was not until the fifth paragraph that the article disclosed those four broker dealers only have selling agreements with one ARC product, Phillips Edison - ARC Grocery Center REIT II.  With all the news surrounding ARCP's accounting issues, it's pathetic that a temporary suspension of one selling agreement is InvestmentNews' lead story.

National Planning Holdings has also prohibited its reps from soliciting trades for other AR Capital listed companies.  In its haste to publish this afternoon's story, InvestmentNews didn't even have time to look up one of the securities National Planning Holdings is barring, ARCPP, which is ARCP's preferred stock.  Irresponsible.

There were two news items today more relevant to ARCP than the suspension of selling agreements for one non-traded REIT.  It is being reported that the SEC is to open an inquiry into ARCP's accounting, and that ratings agencies S&P and Moody's are re-evaluating ARCP's credit ratings.  In the short-term, a cut in ARCP's credit rating could lead to higher borrowing costs.  Bloomberg attributed ARCP's stock decline today to this fear.  ARCP is currently rated Baa-3, one level above a junk rating, and its preferred stock has a rating of Ba1, the highest junk rating.

Come on InvestmentNews, you are better than this afternoon's fear mongering article.

Wednesday, September 10, 2014

Yuck Factor

Here is a Bloomberg article from last week on a unit of insurance giant AIG that is suing a life settlement company.  Life settlements are are described in the article:
In such deals, called life settlements, an investor buys insurance policies from individuals and pays the premiums until they die, when the investor collects the payout. The arrangement becomes less profitable for the investor the longer the person survives.
The division of AIG, Lavastone, hired a life settlement company, Coventry, to buy life insurance policies on its behalf.  The AIG unit is suing Coventry because it bought the life insurance policies cheaper than it knew AIG would pay for the policies and then sold the policies to AIG at a mark-up.

Let's look at this closer:  An insurance company, AIG, forms a division to buy life insurance policies cheap so it won't have to pay the full face amount of the insurance policy when the insured person dies.   "Let's pay $.20 now so we don't have to pay $1.00 later."   AIG had no moral problem buying insurance policies from old or sick people at deep discounts to avoid having to pay the full face value of the insurance, but it gets mad and sues when it found out it paid a deep discount plus a little more. The article didn't state whether Coventry was tasked to buy just AIG policies or could buy any available insurance policies, but I'm sure AIG wanted Coventry to buy AIG policies.  Either way, I don't have much sympathy for AIG.

Life settlement is not a pretty business.

Friday Hijinks

Strategic Storage Trust announced big changes Friday afternoon, September 5, 2014.   It changed its name to SmartStop Self Storage, Inc. and became self managed. As part of the self-management process, SmartStop, through its operating partnership, acquired the operating assets of Strategic Storage Holdings, LLC (SSH), which is the sole member in several affiliated entities.  SmartStop is not, apparently, acquiring its sponsor, Strategic Capital Holdings.  Through SSH, SmartStop expects to receive advisory and property management revenue from the advisors to two REITs in the early stages of their capital raising period, Strategic Storage Growth Trust, Inc. and Strategic Storage Trust II, Inc.

SmartStop acquired SSH's assets for $18 million in cash plus 773,395 units of limited partnership in the REIT's operating partnership.  If the REIT's current $10.81 per share value estimate is used, this puts the SmartStop's cost to acquire the affiliates at $18,000,000 in cash plus $8,360,400 (773,395 units times $10.81), or $26,360,400.  The 773,397 units earn the $.70 per share dividend, or $541,378 per year.  SmartStop had $23.7 million of cash on its balance sheet at June 30, 2014, and the $18 million represents big portion of that reserve. 

In addition, as part of the self-management process, SmartStop granted operating partnership units and Class B operating partnership units to the former advisors of several Strategic Storage entities. The total amount of operating partnership units and Class B units was 1,624,134, which at $10.81 per share is an additional $17,556,889.    The Class B units don't earn distributions until converted to operating partnership units if SmartStop's stock price reaches certain thresholds.  All the operating partnership units earn SmartStop's $.70 per share distribution, which is worth $554,911 per year.

The annual distributions on the newly granted shares total almost $1.1 million per year, a nice yearly stipend. 

SmartStop's letter to investors - which, of course, didn't disclose the price the REIT paid for SSH's assets, you need to go to a filing to find this information - states that the transaction is accretive to the REIT's earnings.  Excellent, I would hope so.  The way SmartStop has historically overpaid its distribution it needs an accretive acquisition.  Seriously, this accretion must be based, in large part, on sales projections and related fee earning potential for the two new REITs.  Both REITs are off to slow equity raises, so I suspect the equity raise projections are more aggressive than actual historical results.   One of the two REITs is private, although it has filed an S-11 to go public, and the second is public, Strategic Storage Trust II.  Through August 2014, Strategic Storage Trust II  had only raised $9.5 million in equity since starting its offering in early January 2014, an inauspicious start.  To its credit, Strategic Storage Trust II did raise $5.5 million in August, its best month since it started its offering.  I don't know how much the private placement has raised.

In the September 5, 2014, investor letter, SmartStop said its two new REITs have $172 million of property under contract on which it can earn fees.  I'd caution that a property under contract is not the same as owning the property.  I know credit criteria has eased in recent years, but you'll still need some fancy financial engineering to buy $172 million of property with only $9 million of equity.  The two REITs need to close the transactions before SmartStop starts to earn fees related to the properties.

There is much about this deal I don't understand.   I am not clear on exactly what SmartStop bought and what it didn't buy.  I don't know the impact of buying operating assets compared to buying entities outright.  I am not sure whether SmartStop bought the SmartStop brand or just the rights to it, and if that is the same thing, or if owning the brand even has any value.  I do not know if worrying about whether SmartStop owns the brand is even a worry.  I do not know when the transaction becomes accretive.  I do know the REIT is now paying out an additional $1.1 million in distributions on all the operating partnership units it issued whether the transaction is immediately accretive or not, and, that after paying out $18 million in cash SmartStop has limited reserves to continue subsidizing its already overpaid distribution.  I am not sure how the value of the transaction was determined.  I am not sure how, if at all, the transaction will impact a liquidity event.  I do not know why I have not read about this deal in any financial press.

Investors were not asked to vote on this $44 million transaction, which doesn't shock me.  I am an optimist at heart, but the pit in my stomach grew as I wrote this post.

I have copied a section from SmartStop's 8-K filed on September 5, 2014, on what SmartStop is purchasing to see whether anyone can make more sense of it:
On September 4, 2014, SmartStop Self Storage, Inc. (formerly known as Strategic Storage Trust, Inc.) (the “Registrant”) and the Registrant’s operating partnership, SmartStop Self Storage Operating Partnership, L.P. (formerly known as Strategic Storage Operating Partnership, L.P.) (the “Operating Partnership”), entered into a series of transactions, agreements, and amendments to the Registrant’s existing agreements and arrangements (such agreements and amendments hereinafter referred to collectively as the “Self Administration and Investment Management Transaction”), with Strategic Storage Holdings, LLC (“SSH”) and the Registrant’s advisor, Strategic Storage Advisor, LLC (the “Advisor”), pursuant to which, effective as of August 31, 2014, the Registrant acquired the self storage advisory, asset management, property management and investment management businesses of SSH. SSH is the sole member of the Advisor and Strategic Storage Property Management, LLC (the “Property Manager”). The Advisor had been responsible for, among other things, managing the Registrant’s affairs on a day-to-day basis and identifying and making acquisitions and investments on the Registrant’s behalf. As a result of the Self Administration and Investment Management Transaction, the Registrant is now self-managed, succeeds to the advisory, asset management and property management arrangements with two additional REITs, Strategic Storage Trust II, Inc. (“SST2”) and Strategic Storage Growth Trust, Inc. (“SSGT”), and has the internal capability to originate, structure and manage additional investment products which would be sponsored by the Registrant.
SSH Contribution Agreement
On September 4, 2014, the Registrant and the Operating Partnership, as Contributee, and SSH, as Contributor, entered into a Contribution Agreement (the “SSH Contribution Agreement”) whereby, effective August 31, 2014, the Operating Partnership acquired substantially all of SSH’s operating assets, including (a) SSH’s 100% membership interests in (i) the Property Manager, (ii) Strategic Storage Opportunities, LLC (“SSO”), (iii) Strategic Storage Realty Group, LLC, the parent company of the advisor and property manager for SST2 and SSGT, respectively, and (iv) Strategic Capital Markets Group, LLC, which owns a 15% non-voting equity interest in Select Capital Corporation, the Registrant’s former dealer manager and the current dealer manager for SST2 and SSGT, (b) all equipment, furnishings, fixtures, computer equipment and certain other personal property as set forth in the SSH Contribution Agreement, (c) all intellectual property, goodwill, licenses and sublicenses granted and obtained with respect thereto (including all rights to the “SmartStop®” brand and “Strategic Storage” related trademarks), (d) all of SSH’s Software as defined in the SSH Contribution Agreement, (e) all of SSH’s processes, practices, procedures and workforce (including a fully integrated operations team of approximately 300 self storage and other professionals), and (f) certain other assets as set forth in the SSH Contribution Agreement, in exchange for $18 million in cash and 773,395 units of limited partnership in the Operating Partnership (“OP Units”).


Thursday, September 04, 2014

The Quiet Liquidity Event

Liquidity events for non-traded REITs have become so routine that Tuesday's announcement that Cole Corporate Income Trust (CCIT) is being acquired by Select Income REIT (SIR) seemed a non-event.  CCIT investors can choose to take $10.50 per share in cash or receive .36 shares of SIR stock for each CCIT share.  Neither the cash option or the stock option can exceed 60% of the total.  The merger values CCIT at $3 billion and is expected to close in early 2015.

The Wall Street Journal's article on the transaction is worth reading, and here is the Bloomberg article on the deal.  American Realty Capital Properties / Cole Capital's press release on the transaction notes that $.20 per share is being paid for incentive fees and transaction costs.  I like this disclosure, as many of these non-traded REITs' liquidity events involve fees to their sponsor firms.  I have not seen the incentive fees so clearly disclosed before and would like to see these listed on all future liquidity events.

Complacency is never good.  Non-traded REITs are long-term, illiquid investments, and liquidity events should not be viewed as a regular occurrence.  The market has favored liquidity events for a few years, but this has not always been the case, and markets can change fast.

Speaking of liquidity events, I was on vacation when the NorthStar Realty Finance (NRF) agreed to acquire Griffin-American Healthcare REIT II in a $4 billion transaction.  By the time I got back to work most of the news on the deal had been out for more than a week making any thoughts I had on the deal stale.  I am still watching for updates and will comment as appropriate.

Tuesday, August 26, 2014

Glad That Passed

Here is a Bloomberg article on the rebound in junk bonds after a brief sell-off in late July and early August.  Yields on junk bonds have dropped to 5.54%, well below their recent high of 6.01% on August 1.  For a few days there I thought the market had come to its senses and was adding a healthy risk premium to junk bonds.  I guess not.

Thursday, August 21, 2014

Note Restructure

InvestmentNews' Bruce Kelly has a good article out this afternoon on the Thompson Note Restructure.  I've had the (dis)pleasure of reading the restructure plan and it affirms my opinion that private notes are tricky, tricky deals.

Wednesday, August 20, 2014

Kite Completes 1-For-4 Reverse Split

Kite Realty (KRG), which completed its merger of Inland Diversified in early July, finalized its 1-for-4 reverse stock last week.  Investors who originally paid $10.00 per share for their Inland Diversified shares received 1.7 KRG shares in early July, and then these shares were subject to last week's reverse split.  The pre-split breakeven price of KRG's stock for an original Inland Diversified investor was $5.88 ($10.00 divided by 1.7).  The new split-adjusted breakeven price is $23.52, by my calculations ($5.88 times 4).

Today, August 20, 2014, KRG closed at $26.13, or the equivalent of $11.11 to an Inland Diversified investor.

Dented Projections

In the 1990s I sat through several Harry Dent presentations at various financial conferences.  Back then, touting one of his books, Dent predicted the Dow reaching 35,000.  In a reversal, he is now warning of a Dow 6,000 - he has another book to sell!  This CBS Money Watch article from 2013 shows how wrong Dent's guesses have been since the '90s.  Dent is about as worthless as pessimist Peter Schiff.  They can't even prove the saying that a broken clock is right twice a day, because apparently they are broken digital clocks, which are never right.   Together, you can call their speculations dented pieces of schiff.  

Tuesday, August 19, 2014

Multifamily Starts and Completions

The monthly housing numbers vary widely. According to a Reuters' article on today's housing figures:
Groundbreaking surged 15.7 percent last month to a seasonally adjusted annual 1.09-million unit pace, the Commerce Department said on Tuesday, snapping two straight months of declines.
It is hard to get a good read on housing through one month's data.   Calculated Risk has two good article on today's figures.  The first, here, summarizes the housing report, and the second, here, gives more insight, and both articles put the housing figures into a wider context.  After reading the two posts I am optimistic about housing's continued strength. 

The data on multifamily starts and completions was interesting, especially after reading and posting Monogram Residential Trust's valuation assumptions yesterday.  Calculated Risk has the following graph:


Multifamily construction starts are approaching levels not seen since the late 1980s.  The added supply have to put pressure on cap rates and rental growth rates as multifamily owners compete with one another.

Monday, August 18, 2014

Monogram Q&A

The Monogram Residential Trust Q&A regarding its recent valuation is worth a read.  It is eye-popping.  This blog has discussed valuation methods before and is not going to regurgitate the topic again.  But it is worth noting that Monogram determined its value, while Duff & Phelps was used to verify Monogram's valuation assumptions and methodologies. 

Monogram valued its operating properties using forward cap rates and rental growth assumptions based on various markets across the country.  Rental growth rates ranged from 1.7% to 4.9%, with an average of 3.4% annually.  Cap rate assumptions ranged from 5.0% on the high end to a low of 4.2%.  Properties under development were valued using similar methodologies: 
These inputs included construction costs, completion dates, lease up rates, rental growth rates, operating expenses, occupancy, capital expenditures, exit capitalization rates, and discount rates.
The question I have is how does this REIT come up with a value of only $10.41 per share when it uses forward projections with rental growth rates over 3% and cap rates under 5%?

Can't Tell The Players Without A Program

Dollar General, Dollar Tree and Family Dollar Stores.  I'll admit, it is hard for me to tell the three discount retailers apart, but look at the portfolio of any retail-focused, net lease real estate investment trust and you'll likely see properties leased to one or more of the three companies.  Too add to the confusion, Dollar General is in a bidding war against Dollar Tree to buy Family Dollar Stores.  To help poor saps like me, all three companies should merge and call the new company Super Dollar. 

Friday, August 15, 2014

Tweet Worthy

I need a twitter account for this blog because some things I read are only worth the 140 characters of a tweet.  In an email today pushing its annual conference, REISA highlighted a session called "The Anatomy Of A Successful Oil and Gas Deal."   Besides hosting a fantasy session, apparently REISA forgot that its full name is Real Estate Investment Securities Association.  A look at the companies sponsoring this year's REISA event includes several oil and gas companies and the sponsor of a dodgy note program. (The notes are backed by life insurance policies - i.e. people have to die to pay interest and principal.)  Good times.

Monogram Seeks To Join Liquidity Bandwagon

Monogram Residential Trust, the formerly named Behringer Harvard Multifamily REIT I, announced yesterday that it plans to list its shares on a national exchange.  Like the Inland American disclosure earlier in the week that it is spinning off its lodging properties, the Monogram news was vague on specifics.  Monogram's board has authorized the start of "the process of exploring a potential listing on a national exchange."  The REIT's board has apparently explored various liquidity options and has decided that a listing provides the best opportunity for investors. 

The REIT made the decision to terminate its share repurchase program and its distribution reinvestment plan even though the listing timing is not clearly defined.  An open-end listing date combined with stoppage of the share repurchase program is an invitation to mini-tender firms to step in and offer low-ball bids for now completely illiquid shares. 

Separately, Monogram announced a new estimated per share value of $10.41 per share, an increase from the $10.03 per share as of March 1, 2013.  I should not have to state this but will any way: remember, the $10.41 is the REIT's estimate per share only and any listing price, or mini-tender offer, will likely vary from this price.

A successful listing - any price near $10.00 per share - for Monogram would not only be positive for investors, but for Behringer Harvard, too.

Thursday, August 14, 2014

No Verruca Of A Deal

It was just a year ago when the $10 billion Inland American REIT announced it was selling $2.3 billion of properties to various American Realty Capital REITs.  Inland American didn't distribute any sale proceeds to investors from that sale.  Inland American announced earlier this week it was forming a separate, publicly traded company for all its lodging assets.  This time, Inland American investors will receive shares in the new company, while retaining shares in Inland American.

The new lodging company is called Xenia Hotels & Resorts, Inc., with a symbol XHR.  The spin-off is expected to be completed in four to eight months and include nearly fifty properties.  Key details, like whether investors are going to have their shares locked up for a certain period, or what the estimated value of the lodging transaction is to an Inland American investor, have not been finalized and were not in Inland American's filing or this InvestmentNews article.  Inland American is focusing on three main property types: lodging, multi-tenant retail and student housing. 

I am glad Inland American picked such an easy name for its new company.  Here is the definition of xenia:
xenia |ˈzēnēə, -nyə|
noun Botany
the influence or effect of pollen on the endosperm or embryo, resulting in hybrid characteristics in form, color, etc., of the derived seed.
After reading that crazy definition of a xenia, I am reminded of the goof name Veruca Salt from Roald Dahl's Charlie and the Chocolate Factory.

Wednesday, August 13, 2014

BREAKING NEWS - INTERVAL FUNDS ARE FUNDS-OF-FUNDS

DATELINE: AUGUST 13, 2014, ALTERNATIVE INVESTMENT UNIVERSE

THIS BLOG HAS DISCOVERED THAT INTERVAL FUNDS ARE FUNDS-OF-FUNDS.  INTERVAL FUNDS RAISE EQUITY TO INVEST IN OTHER INVESTMENT FUNDS, THE DEFINITION OF A FUND-OF-FUNDS.   INTERVAL FUNDS HAVE TWO LAYERS OF FEES... FEES AT THE INTERVAL FUND LEVEL AND FEES AT THE INVESTMENT FUND LEVEL.  ANY RESEARCH OR DUE DILIGENCE REPORT ON INTERVAL FUNDS SHOULD DISCLOSE THIS DATA.

IN A RELATED STORY, THIS BLOG HAS LEARNED THAT THERE IS NOTHING WRONG WITH FUNDS-OF FUNDS.

Cracks in the Credit Facade

Here is a cheery Bloomberg article to start your day.  It goes into detail on a few pending CMBS offerings and how issuers are having to boost yields to get their bonds sold, as investors are worried about credit quality and want to get paid for added risk.  Gee, what a concept.  Like the article I linked to yesterday, there are plenty of facts in this article and I don't want to excerpt key points out of context. 

I will note this quote, though:
Property values in the largest U.S. cities have surpassed their 2007 peaks, encouraging demand, after plunging as much as 42 percent in the aftermath of the credit crisis, according to Moody’s/RCA Commercial Property Price Index .
I have read plenty of articles in recent months about the drop in lending standards.  Investors' search and desire for yield has made them less concerned about credit quality.  It seems a welcome push back has begun.  It needs to spread beyond real estate.  

Monday, August 11, 2014

Big Deal?

I have been away for a week or so recharging the batteries and sharpening my pencil.  I just saw this Reuters article on regulator scrutiny of private equity leveraged loans, which I suspect includes loans made by business development company loans, too.  This seems like a big deal to me and an issue worth watching.    I'm not going to excerpt any portions of the article because no passage makes sense out of context.  The article is short and worth a read.

Tuesday, July 29, 2014

Gibberish With A Dash Of Wisdom

This InvestmentNews article from yesterday has me scratching my head.  It's an opinion piece, loose on facts.  The article is written by the manager of the Resource Real Estate Diversified Income Fund (RREDX), an interval fund that invests a portion of its assets in non-traded REITs.   I am going to address a few points from the article.

This sentence early in the article is an understatement:
The best type of liquidity event is when nontraded REIT investors tend to make a profit on their initial investment.
 Duh.  I'm not sure what I can add to this bit of brilliance.

This specious passage troubled me:
Most liquidations happened in one of three ways:
1) An IPO into the REIT public market
2) A sale to an affiliated publicly traded REIT
3) A sale to a REIT sponsor that is a publicly listed company
Very few non-traded REIT liquidity events involve an Initial Public Offering.  An IPO as part of a listing has a stigma attached to it and indicates a REIT is in financial difficulty.  Does anyone remember Inland Western, now Retail Properties of America's (RPAI) IPO and listing?  An IPO involves raising new equity capital - that is the IPO part - and the few non-traded REITs with IPOs attached have locked up existing shareholders.  This happened with the former Wells Timberland (now Catchmark Timber Trust (CTT)) and BlueRock Residential Growth (BRG). 

A listing of shares not involving an IPO is a more common liquidity event.  Examples include American Realty Capital Trust, American Realty Capital Healthcare Trust (HCT), American Realty New York REIT (NYRT), United Development Funding IV (UDF), Cole Credit Property Trust III (listed as Cole Real Estate Investments)), Wells REIT II (Columbia Property Trust (CXP)), and CB Richard Ellis (Chambers Street (CSG)). 

The second point, the sale of a non-traded REIT to an affiliate requires a listed affiliate, which only applies to a few sponsors.  American Realty Capital, through listed American Realty Capital Properties (ARCP), and WP Carey (WPC) have used this method.  NorthStar Realty Finance (NRF) has the potential to use this strategy, but it has not to date.  Inland has several listed REITs but has not used these traded companies to buy or merge with any other Inland non-traded REIT.

The third point, sale of a non-traded REIT to a listed REIT sponsor, is even more tenuous.  The only example that I can think of is ARCP buying Cole Real Estate Investments last fall.  If the rumored NRF acquisition of Griffin-American Healthcare REIT II ever happens, that would be the second example.  A non-sponsor listed REIT buying a non-traded REIT is more common.  Kite Realty (KRG) purchased Inland Diversified earlier this year and Spirit Realty (SRC) acquired Cole Credit Property Trust II in 2013.  Both acquisitions were positive for the buyers.  Inland sold its second REIT to Developers Diversified (DDR) back in the mid-2000s.  There have been several post-listing acquisitions for former non-traded REITs, too, with Realty Income (O) acquiring American Realty Capital Trust after it listed, and now American Realty Capital Healthcare Trust (HCT) is being acquired by Ventas (VTR). 

If you look at the logic behind point three, it becomes a mute point.  Buying a competitor's non-traded REIT makes that competitor look good by giving it an instant track record and liquidity.  It makes no sense for a sponsor to give this advantage to competitor.  Plus, sponsors make big money during the capital raise and investing period, not so much from managing invested assets.  From a sponsor perspective, it's a poor business decision to buy a fully invested company after this one-time, money making opportunity is gone.

I am sick and tired of the fear-mongering trope about rising interest rates.  This article speaks as if rates have already gone up and stocks have tanked.   The article states:
We have also seen a decrease in the valuation of many of the net lease publicly traded REITs, the asset type that represents approximately two-thirds of the nontraded REIT market, due to concerns about higher interest rates.
Whether or not this is an opinion piece, the statement is wrong.  Check the stock charts of O, SRC, WPC and ARCP.  With the exception of ARCP, all are at, or not far from, 52-week highs, and ARCP is trading strong.  Yields on the ten-year Treasury are below 2.50%, and are down about 50 basis points from the start of the year.  Yes, some day interest rates are going to increase, but it has not happened yet.    

I'll finish on a positive note.  The following statement alone is worth reading the article:
Instead, investors should be prepared to stay in non-traded REIT programs longer and focus on the attractiveness of the investment, rather than an early exit.
Non-traded REITs are long-term investments, not short-term flip vehicles.  Recent liquidity events have been positive for investors, sponsors, and brokers.  I hope it continues.  But any investor in a non-traded REIT should be prepared to hold their investment for the maximum time stated in the offering prospectus, if not longer.

Thursday, July 24, 2014

North Dakota Oil Boom

Here is a short article worth reading from the Fivethirtyeight blog.  It discusses the boom in North Dakota's oil production, primarily in the Bakken Shale formation.  Besides the two startling graphs imbedded in article, this passage stood out:
The issue isn’t whether North Dakota will run out of oil. There’s little doubt that the Bakken Shale, North Dakota’s main oil-producing reservoir, contains billions of barrels of crude. The question is about getting it out. A well’s production rate — how much oil it pumps in a given amount of time — falls quickly, and wells drilled into shale rock like the Bakken decline especially fast, as much as 70 percent in the first year. That means oil production is a treadmill: Companies have to keep drilling just to keep production flat. The more they produce, the more they have to drill to keep up.
The 70% first year decline is incredible.  To help some of the depletion, drillers, through technological advances, have increased well productivity.   Wells on line for at least a month produced 116 barrels a month in 2007, now produce over 500 barrels a month.  

Wednesday, July 23, 2014

Sloppy Work

Recently I read an article and investment report on two finance companies that pay sizable current distributions and interest, all of which are supported by accrued revenue.  Accrued revenue or accrued interest is not paid until an investment or loan matures.  For example, if a company makes a two-year, $1,000,000 preferred equity investment with a 12% accrued interest, in two years the company will receive back the $1,000,000 in principal and $240,000 of interest.  There is a lag before a company realizes accrued revenue. 

If a company is paying a current distribution that is backed by accrued revenue, cash has to come from somewhere until the accrued revenue is realized.  This typically is either through borrowing or equity.  Eventually, as a finance company grows and matures, its flow of realized accrued investments should exceed the amount it pays in distributions. 

This is not yet the full situation in the two finance companies where 100% of their investments are accrued, and their current distributions are being paid through reserves, equity, borrowings, and in one company, some operating cash flow (realized accrued income).  Neither the article nor the investment report noted the accrued income, the time differential between when revenue is booked and when cash is realized, or addressed how the companies were paying current distributions.  This annoys me and it is sloppy work.   I believe the authors did not fully understood the companies they were writing about, which is bad.

There is nothing wrong whatsoever with finance companies that originate or own accrued investments.  If a finance company makes accrued investments with equity or borrowings that require current distributions or interest payments, how the company supports those current distributions or interest payments is important information.  Unfortunately, you would not get this information from the two pieces I read.

Monday, July 21, 2014

Filling A Void

I noted at the end of a post last week that Griffn-American Healthcare REIT II's shareholders are being solicited by a mini-tender firm.  The firm is offering to buy shares at a strong price compared to the REIT's original offer price.  Griffn-American REIT II is not the only non-traded REIT where shareholders are being approached by the mini-tender firms.  Signature Office REIT, the formerly named Wells Core Office REIT, and Strategic Storage Trust are also being targeted by mini-tender firms.  Below is a table with the offer price, tender price, and discount for the three tender offers:


Non-Traded REIT
Orig. Offer Price
Tender Offer
Discount to Offer
G-A Healthcare II
$10.00 to $10.22
$10.00
0.0% to 2.2%
Strategic Storage Tr
$10.00 to $10.79
$7.25
27.5% to 38.8%
Signature Off. REIT
$25.00
$16.00
36.0%
 
All three of the non-traded REITs have terminated or suspended their share repurchase plans as they seek liquidity events, which have spurred the mini-tender firms.  These companies are annoying, to say the least, to non-traded REITs.  The mini-tender firms are money managers - not altruists - looking to acquire shares at cheap prices, not necessarily pay market prices, but they are stepping in to provide a limited form of liquidity where none is available.  The cliche is buyer beware, but in this case, it is seller beware.   

Friday, July 18, 2014

Liquidity Events and Hyperbole

I re-read the Bruce Kelly article I linked to earlier in the week.  The article stated that there were only two liquidity events in the first half of 2014.  Bruce missed a few.  Here are the liquidity events I know of in the first half of 2014:


Liquidity Events First Half of 2014
Fund Month Original Equity (Billions)
ARC Trust IV Jan  $1.7
CPA 16 Global Feb  $1.9
BlueRock Resid.* Feb  $- 
ARC Healthcare April  $1.7
ARC New York REIT April  $1.7
UDF IV June  $0.6
FSIC April  $3.0
TOTAL
 $10.6

In addition to ARC Healthcare and ARC New York REIT, the first half of 2014 saw ARC Trust IV complete its merger into American Realty Capital Properties (ARCP), CPA 16 merge into WP Carey, and the listings of Blue Rock Residential Growth* (BRG) and UDF IV (UDF).  I included the April listing of the first Franklin Square business development corporation, Franklin Square Investment Corp (FSIC), because while not a REIT it was a non-traded investment that provided a liquidity event. 

The strange part of the Kelly article was the Inland executive gloating about Inland Diversified's completed merger with Kite Realty:
The deal has been one of the most successful for nontraded REIT investors in the recent past, Mr. Sabshon said.

He noted that on July 2, the first full trading day for the Inland Diversified/Kite merger, Kite closed at $6.40. At an exchange rate of 1.7, that translates to an Inland Diversified exit value of $10.92, he said.

Excluding nontraded REITs that were purchased by related or affiliated REITs, a common industry practice, the Inland Diversified merger represents the highest nonaffiliated transaction exit price in two years, Mr. Sabshon said.
Yes, Inland Diversified's sale to Kite Realty was a successful liquidity event.  No, it was not the most successful listing of the past two years.  Does anyone remember the Cole Credit Property Trust III listing a year ago?  I believe there was some controversy surrounding this listing, but it opened at $11.50 per share.  The Inland executive's arbitrary exclusion of affiliated liquidity events makes no sense.  Is cash from an affiliated liquidity event worth less than cash from a non-affiliated liquidity event?  The CPA 16 and ARCT III liquidity events were with affiliated entities and traded at values higher than Inland Diversified's 9% premium.  I am taking nothing away from Inland Diversified's listing and its returns to investors, they are commendable and more than respectable, but let's lower the hyperbole. 

*  BlueRock Residential Growth (BRG) only raised about $23 million of investor equity in its multi-year offer period.  BRG's listing involved an IPO where the original investors received three classes of illiquid Class B shares.  The first B class does not convert to liquid shares until twelve months after the listing, and it'll be two years post-listing until original BRG shareholders are fully liquid.  BRG is a listing but should not be considered a liquidity event.   Its equity raise was so small it would not even show on the table above.

Thursday, July 17, 2014

Crap Storm Warning

This afternoon, Strategic Realty Trust disclosed in a SEC filing that it has determined a new net asset value (NAV) of $7.11 per share.  The REIT raised capital at $10.00 per share.  It issued valuation estimates during the offering period that reached $10.60 per share.  This $10.60 per share claim was as recent as early 2013 when it completed its offering period.  The new value represents a 33% decline in NAV in eighteen months, which was during a period of rising commercial real estate values.

This blog talked about Strategic Realty here, where it referenced an InvestmentNews article, and I talked about the REIT's valuation process here. 

This is ugly and someone is going to have to answer some tough questions. 

Starting To Make Sense

I wrote yesterday that I was not going to pay attention to any rumors until they showed up in a Bruce Kelly article.  No sooner than I had posted that comment than I read Kelly's report that NorthStar Realty Finance (NRF) is in talks to buy the Griffin-American Healthcare REIT II.  His story reads as though he sourced it through the same Financial Times article I referenced.  Kelly's article provides a good rundown of recent non-traded REIT liquidity events in addition to NorthStar's potential purchase of Griffin-American Healthcare REIT II.

At first I didn't understand why NRF would spend $3.7 billion to $4.0 billion for a healthcare REIT.  I immediately thought it was a way to combine the NorthStar and Griffin-American non-traded REIT sales platforms.  I have always primarily viewed NRF as a real estate finance company that, to a lesser extent, owned other real estate, including healthcare, manufactured homes and hotels.  Then I read NRF's first quarter 10-Q and the Griffin-American Healthcare REIT II acquisition makes more sense.  NRF hired James Flaherty III in January to build NRF's healthcare business.  From NRF's 10-Q:
In January 2014, NSAM entered into a long-term strategic partnership with James F. Flaherty III, former Chief Executive Officer of HCP, Inc., focused on expanding the Company’s healthcare business into a preeminent healthcare platform (“Healthcare Strategic Partnership”). In connection with the partnership, Mr. Flaherty will oversee and seek to grow both the Company’s healthcare real estate portfolio and the portfolio of NorthStar Healthcare. In addition, the partnership is expected to focus on raising institutional capital for funds expected to be managed by NSAM.
NSAM is the company NRF spun off earlier this month.  NSAM is NRF's asset manager and it or an affiliate will serve as the distributor and advisor for NRF's non-traded REIT business.   Mr. Flaherty is also the CEO and President of NorthStar Healthcare Income, Inc.  In May 2014, NRF acquired a $1.1 billion portfolio of healthcare properties, primarily assisted living and skilled nursing facilities.  NRF now has $1.63 billion of healthcare assets and is seeking to aggressively grow this business, and this explains NRF's interest in the  Griffin-American Healthcare REIT II portfolio.  NRF's first quarter 10-Q is worth a read because it discusses Mr. Flaherty's financial incentives to growth the healthcare business. 

How NRF would finance the Griffin-American Healthcare REIT II acquisition is another consideration, but the rationale for the purchase is clear.

Wednesday, July 16, 2014

LIBOR Plus ?!?!

When United Development Funding IV (UDF) listed on NASDAQ in early June it offered to repurchase up to $35 million of shares at a price of $20.50 per share.  The tender offer was oversubscribed by about three times, which was not unexpected.  UDF, in a filing last week, disclosed that it is financing the entire share repurchase with a $35 million loan from an entity called Waterfall Finance 4, LLC.  The loan has a one-year term and is due July 2, 2015.  UDF is paying LIBOR plus 9.0%, and interest is due monthly.  LIBOR is currently around .25%, so UDF is paying about 9.25% for the money.  I am snarkless.

Shut Up Already

The Financial Times published another apparent non-story last week.  (Sorry, no link to the story but you can Google it.) This one was on the alleged acquisition by NorthStar Realty Finance (NRF) of Griffin-American Healthcare REIT II at a price tag of $3.7 billion to $4.0 billion.  In late May the same FT reporter, Ed Hammond, had a story that Dividend Capital's Industrial Income Trust was looking to sell itself for $4 billion.  I discussed that article here. 

Nothing has happened yet with Industrial Income Trust, and a week and a half later I've read nothing else on a NRF / Griffin-American Healthcare REIT II combination.  In early May, Griffin-American Health REIT II was subject of a Wall Street Journal article on another impending sale that never happened.  I noted the WSJ article here.  I'm not sure what's going on with these rumors, but suspect they are attempts to drive up merger prices by attracting additional potential buyers.  From now on until Bruce Kelly reports a combination I'm not going to take any story seriously.

Based on data in the May Wall Street Journal article, a price of $3.7 billion to $4.0 billion for Griffin-American Healthcare REIT II would result in share price of $12.63 to $13.66.  If the merger leaks are an attempt to drive the price for Griffin-American higher, whoever is blabbing to reporters should stop.  A price per share range of $12.63 to $13.66 is excellent, especially since the REIT finished its equity raise less than a year ago at prices of $10.00 to $10.22 per share and paid a load of 12% on that equity. 

A NorthStar / Griffin-American Healthcare REIT II merger presents more narrative than was addressed in the short FT article.  Both Griffin and NorthStar operate respected syndication businesses.  Where do these play into the merger, if at all?  A combination of this business would be interesting and have more implications than just a single REIT's liquidity event.

Separately, but tangentially, Griffin-American Health REIT II shareholders are being solicited by mini-tender offers.  The companies that issue these tender offers usually make offers at deep discounts to prices paid by investors for their shares.  The current tender offer price for Griffin-American is $10.00 per share, essentially no discount to the price most investors paid for their shares.

Friday, June 20, 2014

Vacancy Sign Flashing

Here is a Bloomberg article on recent transactions in the hotel sector.  It has been an active sector.  I missed the NorthStar (NRF) news last month that entered into a nearly $1 billion joint venture with Chatham Lodging for forty-seven limited service hotels.  The article lists so many transactions it does not even get into some of the back stories, like how American Realty Capital Hospitality Trust, which is in the early stage of its equity raise, is financing the 126 hotels it is buying from affiliates of Goldman Sachs for $1.93 billion. 

I would point out couple of additions to the article.  First, the terms "limited service" and "select service" seem blurred, but are two distinct categories.  Most of the transactions listed in the article have happened in the limited service category, which include brands like Courtyard, Homewood Suites, and Hampton Inns.  Select service is a lower amenity property and includes brands like Days Inns and Super 8.  Management, marketing, pricing and valuations are different for limited service and select service hotels.

Second, the article points out that:
The U.S. hotel industry has recovered since the financial and real estate market meltdown. Room rates in the first five months of this year hit a record, according to Jan Freitag, senior vice president at research firm STR Inc. This year through May, the average price for a hotel stay nationwide jumped to $113.58 a night, up 4.1 percent from a year earlier, according to Hendersonville, Tennessee-based STR.

And, it notes that the volume of deals (again confusion with the term "select service") in 2013 was the most since 2006.  The article does not mention the impact of new hotel supply.  I believe it was much higher in 2006 than current levels.  This means, in part, that an economically sensitive sector will not have the addition of new supply to contend with, which pressures rates and occupancies, when the economy slows.  Of course, high trading values for hotel properties, strong occupancies and increasing room rates is going to attract hotel developers.

Thursday, June 19, 2014

Know The Brand - Part II

InvestmentNews' Bruce Kelly confirms what WP Carey's CEO Trevor Bond said on a conference call last month:  WP Carey has no plans to launch CPA 19 as a follow-on to its previous CPA programs.  Kelly's article is full of good information.